
Rs. 93,241 Crores of bids for Rs. 50,000 Crores on offer, tighter CRR rules and a 7.44% 10-year yield: The Financial Market Strategist explains why India’s money-market plumbing needs attention
November 3, 2026
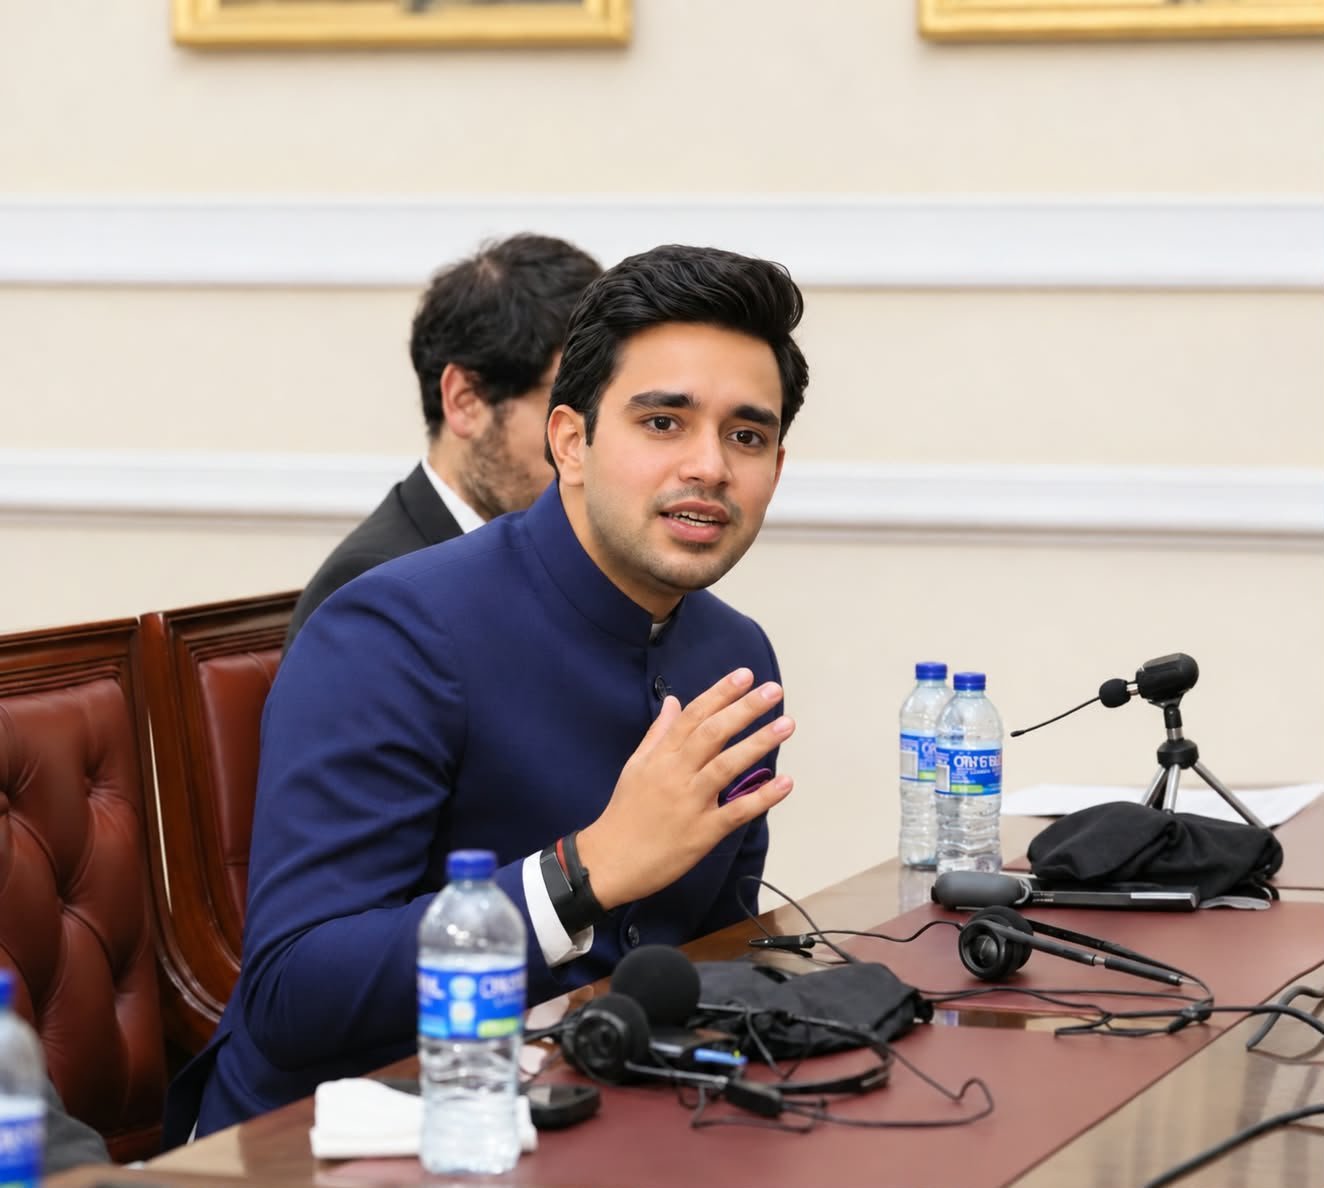
India’s banking system may be approaching a liquidity turning point, and the latest figures demand close attention, according to Lokesh Jangid, Financial Market Strategist, Derivatives Trader and Co-Founder of Nityalakshmi Capital, Telangana.
“Liquidity is not just a technical number in financial markets. It decides how the entire system breathes,” Lokesh Jangid said. “When banks start competing hard for overnight money, the market is sending a signal that deserves much more than a quick look.”
DEMAND NEARLY DOUBLE THE SUPPLY
In a recent overnight Variable Rate Repo (VRR) auction, banks placed bids worth Rs. 93,241 Crores for just Rs. 50,000 Crores on offer. The RBI finally allotted Rs. 50,007 Crores at a cut-off rate of 5.52%. In other words, banks wanted almost 1.86 times the money that was available.
Lokesh Jangid is clear that this does not mean the banking system is heading for a crisis. What it does show, he says, is that the cost and availability of short-term money now need careful watching.
THREE PRESSURE POINTS
A shrinking Surplus – System liquidity reportedly dropped to about Rs. 48,304 Crores on 20 October, as GST payments and other outflows drained available funds. As the surplus thins, banks lose their cushion of spare cash, competition for funds rises and the overnight market begins to feel the strain.
Tighter CRR Compliance – The daily Cash Reserve Ratio (CRR) maintenance requirement has reportedly been raised from 90% to 99%, leaving banks far less room around their reserve obligations. According to Lokesh Jangid, this means less flexibility in day-to-day liquidity management, sharper competition for funds and greater exposure to sudden cash-flow gaps.
The RBI’s Policy Stance – With the repo rate reported at 5.50% and the stance described as calibrated tightening, markets need to track how policy is feeding into real funding costs. “The policy rate is the official price of money. Liquidity tells you how easily you can actually get it. The two are not always the same,” Lokesh Jangid said.
FROM ABSORBING LIQUIDITY TO INJECTING IT
The RBI had reportedly been pulling liquidity out of the system since 6 August. It has now switched to large injections, including a Rs. 1 Trillion VRR auction and a further Rs. 50,000 Crores overnight operation. Lokesh Jangid calls this a significant shift. The key question, he says, is whether it reflects routine management, a short-lived cash mismatch or a more lasting tightening of funding conditions.
BOND MARKET ALREADY SIGNALLING
The RBI reportedly rejected bids at a Treasury bill auction as short-term yields jumped, while the 10-year government bond yield touched around 7.44%. If stress in short-term funding spreads to longer-dated government securities, Lokesh Jangid warns, borrowing costs could rise across the system, hitting corporate finance, bank lending rates, government borrowing and, eventually, the wider economy.
WHAT TO WATCH NEXT
• Call Money Rate vs Repo Rate – Is the premium on overnight funding getting wider?
• Deposit and Lending Rates – Are banks starting to pass higher funding costs on to customers?
• Government Security Yields – Is short-term liquidity stress turning into pressure across the yield curve?
• Future VRR Auctions – Are these one-off interventions, or a sign of a longer-lasting liquidity need?
THE PERSONAL VIEW
“Liquidity stress does not automatically mean a financial crisis, and RBI intervention is not automatically a sign of weakness,” Lokesh Jangid said. “What matters is whether these operations are simply smoothing out temporary gaps, or whether banks are becoming more and more reliant on central-bank money to stay balanced.”
“Liquidity is the plumbing of the financial system. You rarely notice it when it works, but when pressure builds, the effects spread everywhere.”
“Capital matters in markets, but liquidity decides how freely that capital can move,” Lokesh Jangid said. The open question, he adds, is whether India is seeing a needed reset of monetary conditions, a passing squeeze, or the first signs of deeper funding stress.
BEYOND THE PROFESSIONAL
At 26, Lokesh Jangid has established himself as a Financial Market Strategist and emerging entrepreneur with an international professional outlook. His professional journey includes an association with BlackRock’s New York office, where he secured an annual compensation package of $160,000. An Investment Banking professional and IIM graduate, with FRM credentials from GARP and Bentley University, he brings a multidisciplinary understanding of financial markets, derivatives, investment strategy and risk management. He currently serves as Co-Founder of Nityalakshmi Capital, Telangana. His professional approach combines quantitative thinking, macroeconomic awareness and disciplined capital management. Lokesh believes that financial success is not a consequence of speculation, but the outcome of informed decisions, calculated risks and consistent execution.


Leave a comment