
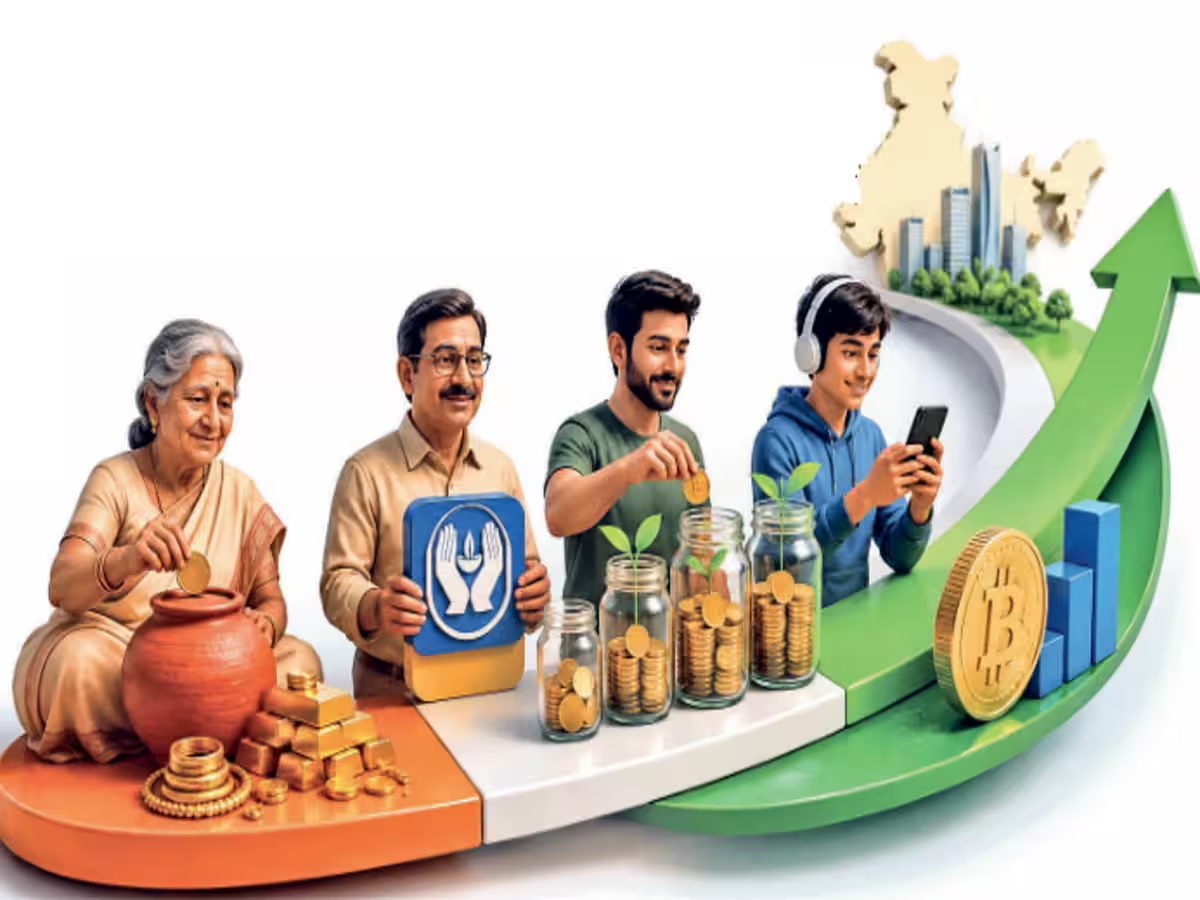
Millennials in India are rethinking how they spend, save and invest their money as living costs, career priorities and financial responsibilities evolve. While lifestyle purchases and digital shopping remain popular, many young professionals are placing greater importance on emergency savings, long-term goals and financial security.
Why Millennials Are Rethinking Their Spending Habits
Millennial spending habits in India are changing as young professionals balance lifestyle aspirations with rising financial responsibilities. Millennials, generally defined as people born between 1981 and 1996, have experienced the transition from traditional shopping and cash payments to online marketplaces, digital banking and instant payment systems.
This generation has greater access to financial information, investment platforms and digital payment services than previous generations did at the same age. At the same time, many face expenses related to housing, education, healthcare, family support and long-term financial goals.
For some millennials, the priority is no longer simply earning enough to maintain a desired lifestyle. They are also thinking about how much they can save, whether they can afford a home, how to prepare for emergencies and how to build wealth over time.
This does not mean that millennials have stopped spending on travel, entertainment, fashion or technology. Instead, some consumers are becoming more conscious of how everyday purchases affect their broader financial plans.
The Influence of Online Shopping and Digital Payments
The growth of e-commerce and digital payments has made shopping more convenient for Indian consumers. Smartphones allow users to compare prices, discover new products, use discount offers and complete purchases within minutes.
For millennials, this convenience can be both an advantage and a challenge. Online platforms make it easier to find competitive prices and access products that may not be available locally. However, personalised advertisements, limited-time offers and influencer recommendations can also encourage purchases that were not originally planned.
Digital payments add another dimension to the experience. Transactions through the Unified Payments Interface (UPI) are quick and widely used, reducing the need to carry cash. Yet the ease of making a payment can sometimes make it harder to track small expenses across the month.
A series of modest purchases can become a significant expense when combined. Food delivery, subscriptions, transport, online shopping and entertainment may each appear affordable individually, but their cumulative cost can reduce the money available for savings.
Tracking spending through bank statements, payment histories or budgeting applications can help consumers understand where their money goes and identify expenses that no longer provide sufficient value.
Lifestyle Spending Versus Long-Term Financial Goals
Lifestyle spending remains an important part of consumer behaviour. Millennials may spend on travel, restaurants, fitness memberships, gadgets, branded clothing and entertainment because these purchases offer convenience, enjoyment or social connection.
The challenge arises when lifestyle expenses consistently take priority over essential financial goals. A person who spends most of their monthly income may struggle to handle an unexpected medical bill, a period without employment or an urgent family expense.
Financial planning does not require eliminating every discretionary purchase. It involves deciding how much money can reasonably be spent after essential expenses, savings and financial commitments have been considered.
For example, someone planning an annual holiday can estimate the total cost in advance and save a fixed amount every month. This approach reduces the need to rely on credit cards or loans when the trip arrives.
Similarly, consumers can set separate budgets for shopping, dining and entertainment. Such limits make spending decisions clearer without removing the flexibility to enjoy occasional purchases.
The goal is to make lifestyle choices compatible with financial stability rather than treating the two as competing priorities.
Emergency Funds Are Becoming an Important Priority
An emergency fund is money kept aside for unexpected expenses or temporary income disruptions. It can help households manage situations such as job loss, urgent repairs, medical costs or other unplanned financial needs without immediately borrowing money.
For millennials managing rent, loan repayments, household bills and family responsibilities, an emergency fund can provide an additional layer of protection.
A common financial planning guideline is to build savings equivalent to three to six months of essential living expenses. The appropriate amount depends on individual circumstances, including income stability, dependants, existing insurance and the availability of other financial support.
Someone with irregular freelance income or substantial family responsibilities may need a larger reserve. A salaried employee with fewer commitments may build savings gradually towards a suitable target.
Starting small can make the process more manageable. Setting aside a fixed amount after receiving a salary, even if the initial contribution is modest, can establish a consistent habit.
Emergency savings should generally remain accessible and be held in relatively low-risk options appropriate to the purpose. Money intended for emergencies should not be exposed to unnecessary market risk.
How Millennials Are Approaching Investments and Wealth Creation
Financial planning extends beyond saving money in a bank account. Some millennials are exploring mutual funds, systematic investment plans, stocks, retirement products and other investment options to work towards long-term goals.
Digital investment platforms have made financial products easier to access, while online educational content has introduced more people to concepts such as compounding, diversification and risk tolerance.
However, greater access does not automatically lead to better investment decisions. Social media discussions can create unrealistic expectations about returns, particularly when creators promote speculative assets or highlight exceptional profits without explaining the associated risks.
Before investing, individuals need to understand their financial goals, time horizon and ability to tolerate losses. High-interest debt and immediate financial obligations may also need attention before taking significant investment risks.
Diversification can help reduce dependence on a single asset, although it cannot eliminate the possibility of losses. Investors should also consider applicable fees, taxes, liquidity requirements and the credibility of financial service providers.
For long-term goals such as retirement or a child’s education, a consistent and informed approach may be more useful than frequently changing investments in response to market headlines.
Credit Cards, Buy Now Pay Later and Responsible Borrowing
Credit cards and Buy Now, Pay Later services allow consumers to purchase products without paying the entire amount immediately. When used carefully, these facilities can help manage cash flow and provide payment flexibility.
Problems can arise when borrowing becomes a routine way to fund discretionary purchases rather than a temporary financial tool. Multiple small instalments can accumulate, leaving consumers with less disposable income in future months.
Credit card balances that are not paid in full may attract interest and other charges under the card’s terms. Missing payments can also affect a borrower’s credit history and future access to credit.
Before choosing an instalment plan, consumers should review the total payable amount, repayment dates, interest, late-payment charges and other conditions. A product advertised as interest-free may still involve fees or restrictions.
A practical rule is to consider whether a purchase would remain affordable after accounting for existing loan payments and essential expenses. If repayment depends on receiving uncertain future income, postponing the purchase may be the safer option.
Responsible borrowing means understanding the commitment before accepting it, not merely checking whether the initial payment fits the monthly budget.
Financial Planning in India’s Tier-2 and Tier-3 Cities
Spending and saving decisions can look different in smaller Indian cities, where household expenses, employment opportunities and access to services vary considerably.
In cities such as Nagpur, Indore, Nashik, Jaipur and Lucknow, some households may face lower housing costs than in India’s most expensive metropolitan areas. However, this is not universal, and expenses depend on neighbourhoods, family needs, commuting patterns and lifestyle choices.
Many young professionals in smaller cities also support parents, contribute to household expenses or save towards property purchases and family responsibilities. These commitments can shape how much money remains available for personal spending and investments.
Digital banking and online financial services have widened access to payment and investment products beyond major metropolitan areas. At the same time, financial education remains important because online access can expose consumers to misleading investment claims and fraudulent schemes.
Simple practices can make a meaningful difference: maintaining a monthly budget, comparing loan terms, reviewing insurance needs and checking investment information through credible sources.
Financial planning should reflect an individual’s actual income and obligations rather than follow a lifestyle model promoted online.
Practical Ways to Build Better Money Habits
Millennials who want greater control over their finances can begin with a few consistent actions.
First, record income and expenses for at least one month. This provides a realistic picture of spending patterns and reveals categories where adjustments may be possible.
Second, automate savings where feasible. Moving a predetermined amount into a savings account after payday can reduce the temptation to spend money intended for future goals.
Third, separate short-term and long-term objectives. Money needed soon for rent, emergencies or a planned purchase should be managed differently from investments intended for goals many years away.
Fourth, review recurring subscriptions and digital purchases regularly. Cancelling unused services or reducing unnecessary spending can free up money without requiring major lifestyle changes.
Finally, avoid comparing personal finances with the lifestyles shown on social media. Online posts rarely reveal a person’s income, debt, family support or financial obligations.
The most useful financial plan is one that can be maintained over time. Small, repeatable decisions can help people balance present needs with future security.
Key Takeaways
- Millennials are balancing lifestyle spending with savings, investments and long-term financial goals.
- Digital payments and online shopping offer convenience but can make frequent, small purchases harder to track.
- Emergency funds, responsible borrowing and informed investing are important parts of personal financial planning.
- Budgeting should reflect actual income, household commitments and individual goals rather than social media expectations.
Frequently Asked Questions
1. Why are millennials changing their spending habits?
Many millennials are balancing lifestyle aspirations with rising living costs, family responsibilities, housing goals and the need for financial security. Individual priorities vary according to income and circumstances.
2. How much should millennials save every month?
There is no single amount suitable for everyone. Savings should depend on income, essential expenses, outstanding debt and financial goals. Starting with a manageable fixed amount and increasing it when possible can help establish consistency.
3. What is the importance of an emergency fund?
An emergency fund helps cover unexpected expenses or temporary income loss without relying entirely on loans or credit cards. A common guideline is to save three to six months of essential living expenses, adjusted to personal circumstances.
4. How can millennials reduce unnecessary spending?
Tracking expenses, setting category-wise budgets, reviewing subscriptions and waiting before making non-essential purchases can help reduce impulse spending. Comparing prices and reviewing credit terms can also support better decisions.



Leave a comment